Specialist Mortgage Broker for Folkestone, Hythe, Sandgate & CT20
With High Speed 1 (HS1) trains linking Folkestone Central and Folkestone West to London St Pancras International in under 55 minutes, a transformed Harbour Arm and Creative Quarter, the grand cliff-top squares of The Leas and the West End (CT20), the coastal charm of Sandgate, and the historic Cinque Port of Hythe and Saltwood (CT21), the Folkestone & Hythe district has become one of Kent's most dynamic coastal property hotspots.
At Transparent Mortgage Services (TMS), we provide independent, whole-of-market mortgage advice for buyers, homeowners and landlords across CT19, CT20 and CT21. Positioned just across the East Sussex / Kent border—connecting seamlessly with our Hastings and Tunbridge Wells mortgage advisor hubs—we combine coastal property expertise with access to over 90 UK mortgage lenders.
HS1 Commuter Affordability, First-Time Buyers & Family Homes in CT19, CT20 & CT21
Many buyers in Folkestone's West End (Around Radnor Park, Grimston Avenue, Earls Avenue and Clifton Gardens), Cheriton, Sandgate, Saltwood and Hythe commute two or three days a week into London on HS1 while enjoying coastal living. How lenders treat your travel costs and income structure has a direct impact on how much you can borrow for a first-time buyer purchase or family move:
By matching your working pattern and income to the most generous lender affordability model before you make an offer in Folkestone or Hythe, we ensure your budget stretches as far as safely possible.
- Season ticket vs flexible hybrid rail costs: If your contract or employer confirms hybrid/remote working so you only travel to St Pancras or Stratford International a couple of days a week using Flexi Season or pay-as-you-go tickets, we select lenders that don't automatically deduct a full £6,500+ annual season ticket from your affordability.
- Up to 5.5x income multiples for professionals & higher earners: Ideal for buyers purchasing family houses in Saltwood, Hythe hillsides, Sandgate or the Folkestone West End school catchments (including The Harvey Grammar School and Folkestone School for Girls).
- 5% and 10% deposit mortgages in Cheriton, Broadmead & East Cliff: Helping local first-time buyers step onto the ladder in CT19 and CT20 with extended 35-to-40-year terms or Joint Borrower Sole Proprietor (JBSP) family support.
- Self-employed, company directors & creative freelancers: Whether you run a business in Folkestone's Creative Quarter, work as a day-rate IT contractor or trade as a CIS subcontractor across Kent, our Self-Employed & Company Director Mortgage Guide explains how we use 1 year's accounts or salary plus retained net profit.
The Leas, West End Leasehold Flats, New Developments & Coastal Underwriting
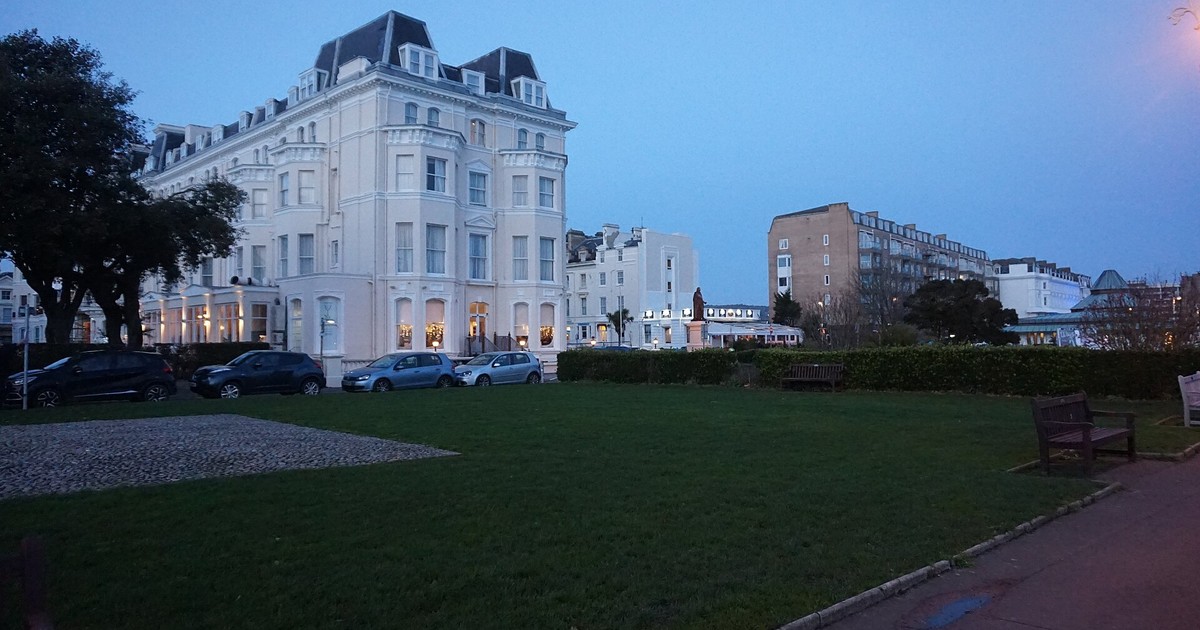
Folkestone and Sandgate feature a wide mix of grand Victorian/Edwardian mansion blocks along The Leas, Clifton Crescent and Trinity Crescent, converted period townhouses, and contemporary seafront developments such as Shoreline. When arranging a mortgage on a CT20 or CT21 apartment, we pre-screen the property for:
Addressing lease length, ground rent, service charge and building height rules upfront avoids costly valuation rejections.
- Lease length and share-of-freehold terms: Ensuring flats with 72–84 years remaining are placed with lenders that accept shorter leases, or structuring a simultaneous lease extension.
- Multi-storey mansion blocks, lifts and EWS1 / cladding checks: For blocks of five or more storeys along The Leas or seafront, we verify lift requirements, balcony construction and fire safety documentation against each lender's current policy.
- Mixed-use buildings around the Old High Street, Tontine Street & Rendezvous Street: Sourcing lenders comfortable with residential flats above or adjacent to independent shops, studios and restaurants.
- Coastal slope stability & flood zone checks: Parts of Sandgate, Lower Leas and the Romney Marsh approaches toward Dymchurch and Hythe require clear surveyor comments and standard buildings insurance availability.
Buy-to-Let, Limited Company (SPV), HMOs & Holiday Lets in Folkestone & Hythe
Ongoing regeneration around Folkestone Harbour and seafront, coupled with strong tenant demand from HS1 commuters, William Harvey Hospital staff (a short hop up the M20) and local families, makes CT19 and CT20 highly attractive for investors. We advise across standard Buy-to-Let, Limited Company (SPV) Buy-to-Let, HMO mortgages and coastal Holiday Lets.
As explained in our 2026 Limited Company SPV & HMO Buy-to-Let Guide, buying in an SPV with SIC code 68209 or 68100 gives higher-rate taxpayers access to 125% rental stress tests and corporation tax deductibility on mortgage interest. For HMOs and Multi-Unit Freehold Blocks (MUFBs) in central Folkestone or Cheriton, we also source lenders offering commercial yield valuations where appropriate.
Remortgaging & Fixed-Rate Renewals
If your fixed rate in Folkestone, Sandgate or Hythe is coming to an end in the next six months, our remortgage service locks in a competitive rate early and switches you downward if rates drop before completion. For homeowners aged 55+ in Hythe, Saltwood and Sandgate, we also provide whole-of-market comparisons across later-life repayment mortgages, Retirement Interest-Only (RIO) mortgages and Lifetime Mortgages (Equity Release) (read our 55+ Later-Life & RIO comparison guide), alongside guaranteed level-premium Life Cover, Critical Illness and Income Protection.
Your home may be repossessed if you do not keep up repayments on your mortgage.
Speak to TMS
Buying, remortgaging or investing in Folkestone, Sandgate, Hythe or Saltwood? Contact TMS today for a free, no-obligation chat with a local mortgage adviser.
Frequently Asked Questions
Do HS1 train ticket costs reduce how much I can borrow for a Folkestone home?
If you commute five days a week, lenders factor in your season ticket cost. However, if your employment contract or employer letter confirms hybrid or home-based working so you only travel to London part-week, many lenders reduce or waive the season ticket deduction.
Can I get a mortgage on a converted Victorian flat on The Leas or in Folkestone's West End?
Yes. We regularly arrange mortgages on converted leasehold and share-of-freehold flats across CT20, matching lease length, service charges, building storeys and commercial proximity to the right lender criteria.
Is it better to buy a Folkestone Buy-to-Let or HMO in a Limited Company (SPV)?
For many higher-rate taxpayers and portfolio builders, an SPV Limited Company (SIC 68209/68100) offers a lower 125% rental stress test and allows mortgage interest to be offset against corporation tax, though you should always confirm the tax position with your accountant.
Can I get a Holiday Let mortgage for a seafront apartment in Folkestone, Sandgate or Hythe?
Yes. Specialist holiday let lenders assess low-, mid- and high-season weekly rental projections from an approved letting agent and often permit Airbnb bookings plus up to 60–90 days of personal owner use.
How early can I lock in a remortgage rate in Folkestone or Hythe?
You can secure a new fixed rate up to six months before your current deal ends. If rates fall before your switch completes, we move you onto the lower deal at no extra cost.