Specialist Mortgage Advice for Rye, Camber Sands, Winchelsea & TN31
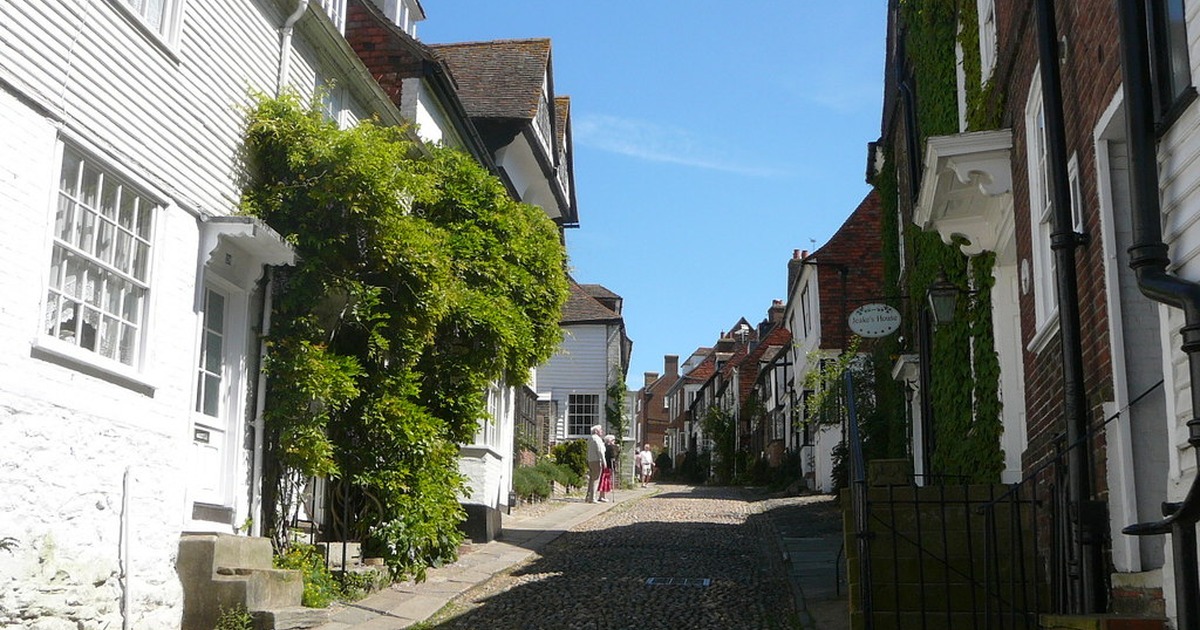
The TN31 postcode—spanning the hilltop citadel of Rye, the sweeping dunes of Camber Sands, the historic grid of Ancient Winchelsea, coastal Winchelsea Beach and Pett Level, and the rural parishes of Peasmarsh, Iden, Playden, Beckley and Rye Harbour—is one of the most distinctive property markets in the South East. Buying, refinancing or investing here involves property types that regularly trip up automated high street underwriting: medieval timber-framed houses on Mermaid Street, Grade II* listed Georgian homes, holiday cottages near the beach, mixed-use High Street buildings, and coastal homes in flood or erosion zones.
At Transparent Mortgage Services (TMS), we act as an independent, whole-of-market mortgage and protection broker for homeowners, relocators, second-home buyers and holiday-let investors across TN31. Working alongside our established Hastings mortgage broker and Bexhill mortgage broker teams, we pair local property knowledge with direct underwriter access.
Financing Period, Listed & Conservation Area Homes in Rye & Winchelsea
Inside Rye's Citadel and across Winchelsea town, properties date from the 14th to the 19th centuries. While buyers fall in love with cobbled lanes, exposed oak beams, hung tiles and historic cellars, mortgage valuers scrutinise specific structural and legal elements:
Because we place mortgages on historic East Sussex properties every week, we check the property's exact characteristics before submitting your application, steering clear of lenders with rigid automated property filters.
- Flying freeholds and creeping freeholds: Common in tightly packed Rye lanes where an upper bedroom or cellar extends above or beneath a neighbour's title. Some lenders cap flying freeholds at 10%–15% of floor area; others accept higher percentages with title indemnity insurance.
- Grade I, Grade II* and Grade II listed buildings: Standard high street lenders often accept Grade II listings but tighten criteria on Grade II* or historic timber-frame infills. We match your RICS Level 3 building survey findings to lenders with pragmatic heritage underwriting.
- Mixed-use and commercial proximity: Flats or cottages above or immediately adjacent to independent shops, galleries, cafes and pubs along The Mint, High Street or Hilders Cliff require lenders comfortable with commercial adjacency and restaurant odour/noise policies.
- Coastal construction, flat roofs and timber cladding: Around Camber Sands, Rye Harbour and Pett Level, properties often feature modern architectural cladding, extensa flat roofs or older timber-frame chalets. Choosing a lender that accepts the specific wall, roof and foundation construction saves weeks of wasted time.
Holiday Let & Second-Home Mortgages in Camber Sands, Rye & Pett Level
Rye and Camber Sands are premier UK coastal staycation destinations, drawing year-round visitors for the beach, Rye Jazz Festival, Rye Bay Scallop Week, Dungeness and the Romney Marsh. If you are purchasing or remortgaging a short-term let, our specialist Holiday Let mortgage service gives you access to building societies and specialist lenders specifically designed for furnished holiday lets.
How 2026 Holiday Let mortgages work in TN31:
- Seasonal rental projection underwriting: Instead of relying on standard long-term rental figures, holiday let lenders assess an approved letting agent's projection of low-, mid- and high-season weekly tariffs ( typically over 30–32 weeks of occupancy).
- Personal use flexibility: Many holiday let mortgage products allow you and your family to enjoy the property in Rye or Camber for up to 60–90 days per year alongside commercial letting.
- Airbnb and short-stay acceptance: Not all lenders permit Airbnb or short breaks under 7 nights; we source lenders that explicitly allow flexible digital platform bookings.
- SPV Limited Company vs personal ownership: Many investors now purchase coastal lets or standard buy-to-let properties through a Limited Company (SPV). Read our 2026 Limited Company SPV & HMO Guide for full details on stress tests and the 5% additional property Stamp Duty surcharge.
Flood Risk, Coastal Insurance & Environmental Checks in TN31
Parts of the Rother Levels, Rye Harbour, Camber and Pett Level sit within Environment Agency flood zones or behind coastal sea defences. Mortgage lenders will always require that a property can obtain standard buildings insurance including flood cover on normal terms.
Before you commit to survey and legal costs on a coastal or marshland property in TN31, we advise checking Flood Re eligibility (which covers most residential properties built before January 2009, excluding commercial buy-to-lets and certain leasehold blocks) and obtaining a firm buildings insurance quote early. Addressing flood zone questions upfront with the lender's valuation team keeps your purchase on track.
Residential Buyers, Commuters, Self-Employed & Later-Life Borrowers
Beyond tourism and heritage homes, TN31 is home to thriving family communities in Rye, Peasmarsh, Beckley, Iden and Broad Oak. With high-speed rail connections via Ashford International (just 20 minutes from Rye on the Marshlink line, connecting to London St Pancras in 38 minutes), Rye is also a popular base for hybrid London commuters and business owners.
We support local first-time buyers, family upsizers needing residential mortgages, and self-employed business owners, hospitality operators and company directors using 1 year's accounts or retained company profits. For homeowners aged 55+ in Rye, Winchelsea and Peasmarsh, we also provide whole-of-market advice across later-life mortgages, RIOs and equity release, explained in our 2026 Later-Life & RIO comparison guide—backed by comprehensive life cover, critical illness and income protection.
Your home may be repossessed if you do not keep up repayments on your mortgage.
Speak to TMS
Looking for a residential, remortgage or holiday let mortgage in Rye, Camber, Winchelsea or Peasmarsh? Contact TMS today for a free, no-obligation chat with a local mortgage adviser.
Frequently Asked Questions
Can I get a mortgage for an Airbnb or holiday let in Rye or Camber Sands?
Yes. Specialist holiday let lenders assess affordability using seasonal low-, mid- and high-season rental projections from a reputable holiday letting agent, and many allow Airbnb bookings plus up to 60–90 days of personal use a year.
Are flying freeholds in Rye's Citadel mortgageable?
Yes. Many high street and building society lenders accept flying freeholds on period houses in Rye, usually up to 10%–20% of the total floor area, often supported by a low-cost flying freehold indemnity policy arranged by your solicitor.
Does flood risk in Camber or Rye Harbour stop you getting a mortgage?
Not automatically. Lenders primarily want confirmation that buildings insurance with flood cover is available at reasonable terms (including via the Flood Re scheme for eligible residential homes built before 2009) and a satisfactory surveyor report.
Can hospitality business owners or seasonal traders in TN31 get a mortgage?
Yes. We work with lenders that assess self-employed sole traders and company directors pragmatically, using either your latest year's accounts, a two-year average, or salary plus retained net profit inside your Limited Company.
How fast can I get an Agreement in Principle for a property in Rye?
Once we have reviewed your income and credit profile, we can usually issue a fully checked Agreement in Principle within 24 hours so you can put forward a strong offer with Rye estate agents.