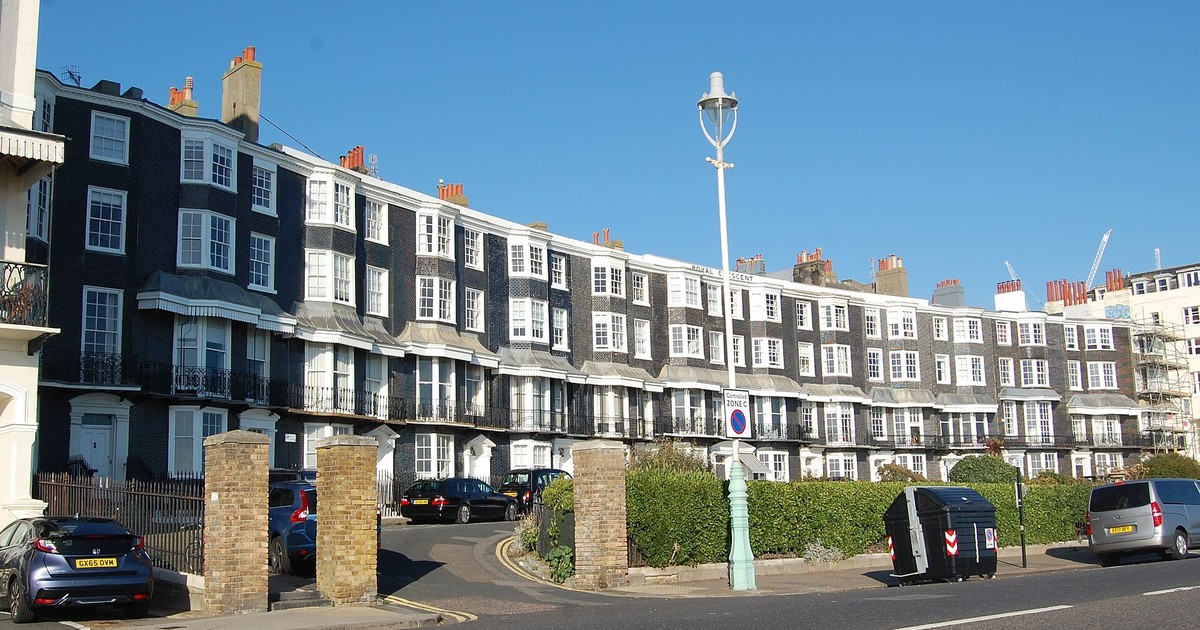
Along the Sussex coast — particularly in Brighton & Hove (Kemptown, Marine Parade, Charlotte Street, Regency Square, and Brunswick Town), St Leonards-on-Sea (Warrior Square, Marina, and Eversfield Place), Hastings, and Eastbourne — grand five- and six-storey Regency and Victorian townhouses have been subdivided over decades into studio flats and compact one-bedroom apartments.
While these period coastal flats are hugely popular with first-time buyers, commuters, and buy-to-let investors due to their seafront locations and strong rental yields, buyers frequently hit an unexpected wall with high-street mortgage lenders as soon as the RICS valuer measures the internal floor area at under 30 square metres (30m² / 323 sq ft) — or when a buyer looking for a Buy-to-Let mortgage does not currently own their own residential home.
At Transparent Mortgage Services (TMS), we regularly place residential and Buy-to-Let mortgages on compact converted coastal flats — including flats measuring 24m² to 29m² (258 to 312 sq ft) and Non-Homeowner Buy-to-Let purchases — by matching the exact layout of the flat to the right lender's underwriting rulebook before you risk a non-refundable valuation fee.
Why 30 Square Metres (30m² / 323 sq ft) Is the Key Cut-Off — And Why Layout Matters as Much as Size
In UK mortgage underwriting, lenders measure property size in square metres (m²) from the Energy Performance Certificate (EPC) and the RICS surveyor's laser measurement, where 30m² equals approximately 323 square feet (sq ft), and 24m² equals approximately 258 sq ft.
Crucially, mortgage underwriters make a major distinction between two property types that estate agents often lump together:
- Open-Plan Studio Flats: Where the bed, living area, and kitchen/kitchenette are within a single open-plan room (with a separate bathroom or shower room).
- Compact 1-Bedroom Converted Flats (20m²–29m² / 215–312 sq ft): Where a period townhouse conversion has a small but physically separate bedroom with its own door and window, separate from the lounge/kitchen area, even though the total Gross Internal Area (GIA) on the EPC or valuation report is 24m² to 29m² (258 to 312 sq ft).
Many high-street banks apply a rigid 30m² (323 sq ft) minimum internal floor area across all flats and automatically decline anything smaller at valuation. However, select lenders on our panel restrict the 30m² rule strictly to open-plan studios and impose no minimum square meterage on converted flats that have a separate bedroom.
Residential vs Buy-to-Let Rules on Compact Coastal Flats (24m²–30m² / 258–323 sq ft)
How much choice you have depends heavily on whether you are buying the flat to live in yourself (Residential) or as an investment property (Buy-to-Let):
- Residential Purchases (Buying to Live In): If you are buying a compact flat or studio to live in yourself, you have a good range of mainstream and specialist options. Several high-street lenders on our panel do not enforce a blanket 30m² (323 sq ft) cut-off on period coastal conversions, relying instead on the RICS valuer's assessment of local resale demand, while manual-underwriting building societies can consider compact studios down to 15m²–25m² (161–269 sq ft).
- Buy-to-Let Purchases (Landlords & Investors): For Buy-to-Let, lender choice on flats under 30m² (323 sq ft) is far more restricted, as the majority of mainstream BTL lenders enforce a hard 30m² or 35m² floor-area minimum. However, we have access to select mainstream Buy-to-Let lending with no minimum square meterage on 1-bedroom converted flats (including 24m² / 258 sq ft conversions) where the flat has a separate bedroom and strong coastal rental demand, alongside specialist BTL lenders for open-plan studio investments.
- Open-Plan Studio LTV Caps: Where a flat is an open-plan studio rather than a separate-bedroom conversion, certain mainstream lenders require a minimum floor area of 30m² (323 sq ft) and cap borrowing at 65% to 75% Loan-to-Value (LTV), making it essential to select the right lender before submitting an application.
Real Brighton Case Study: 24m² (258 sq ft) Converted Flat & Non-Homeowner Buy-to-Let (Charlotte Street & Marine Parade, Kemptown BN2)
To illustrate how these criteria work in practice on Brighton's Regency seafront, here is a real (anonymised) case handled by Transparent Mortgage Services:
- The Client's Situation: Our client lived in Brighton with his partner in her £600,000 home (which was owned in her sole name). He had previously owned a property himself and held £70,000+ in savings that he wanted to invest into a Brighton Buy-to-Let flat in Kemptown (Charlotte Street / Marine Parade, BN2).
- The Double Underwriting Hurdle: First, almost all high-street Buy-to-Let lenders automatically decline Non-Homeowner Buy-to-Let applicants (insisting that all BTL borrowers must currently own a UK residential home in their own name). Second, the initial Regency conversion flat on Charlotte Street, Brighton measured just 24 square metres (24m² / 258 sq ft) on the EPC — 6m² below the standard 30m² high-street cut-off.
- How We Placed It at Mainstream Rates: Because the client had previously owned property and lived with his partner who owned their home, we matched the case to one of the very few mainstream Buy-to-Let lenders on our panel that accepts both Non-Homeowner Buy-to-Let investors and compact 24m² (258 sq ft) converted flats (subject to valuer marketability) at normal high-street rates rather than expensive specialist rates. We obtained underwriter acceptance on the 24m² Charlotte Street flat and subsequently completed the client's Kemptown seafront purchase on Marine Parade, Brighton (BN2) (£300,000 purchase price, £150,000 mortgage on a 4.19% 5-year fixed rate).
3 Steps to Take Before Making an Offer on a Brighton, Hove or St Leonards Flat
- Check the EPC Floor Area First (m² & sq ft): Before paying a non-refundable mortgage valuation fee, check the property's Energy Performance Certificate (EPC) on the government register. It lists the exact Total Floor Area in square metres (m²) (multiply by
10.764to convert to square feet). If it reads between 20m² and 32m² (215 to 344 sq ft), tell us before you apply so we avoid lenders with automated 30m² rejections. - Check the Floorplan (Separate Bedroom vs Open-Plan Studio): A 24m²–29m² (258–312 sq ft) flat with a separate bedroom opens up mainstream residential and Buy-to-Let lenders that would otherwise decline an open-plan studio of the exact same square footage.
- Check Lease Length, Ground Rent & Building Height: In Regency terraces along Marine Parade (Brighton), Brunswick Terrace (Hove), or Warrior Square and Marina (St Leonards-on-Sea), buildings are often 4 to 6 storeys high with converted basements. We check the unexpired lease term (ideally 85+ years, or whether a share of freehold is included), service charges, and building storey height alongside the floor area.
Speak to Sussex's Specialist Coastal Flat & Buy-to-Let Mortgage Brokers
Whether you are buying a compact 24m²–30m² (258–323 sq ft) Regency conversion flat, an open-plan studio apartment, or applying as a Non-Homeowner Buy-to-Let investor in Brighton, Hove, St Leonards-on-Sea, Hastings, or Eastbourne, Transparent Mortgage Services (TMS) knows which lenders will approve both you and the property first time.
Call our team on 01424 444597, email info@TMS-FS.co.uk, or request a free initial consultation online.